
Black Friday BNPL: Build a Repayment Calendar First
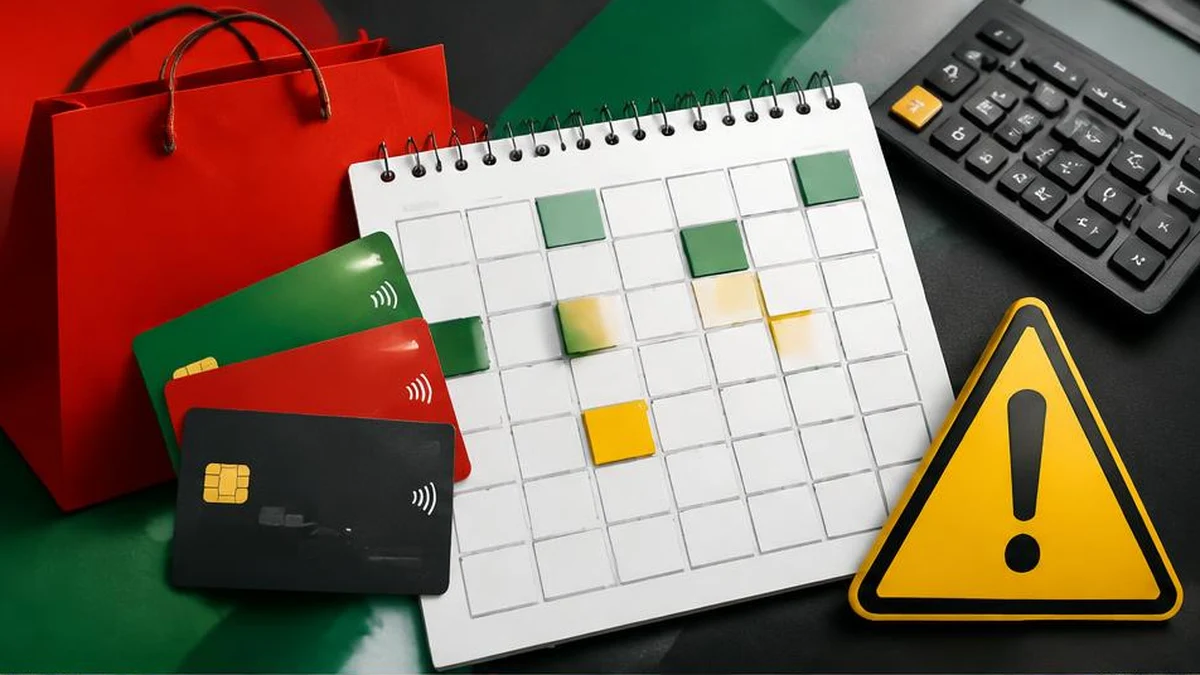
A small first instalment can hide a crowded repayment schedule. Compare the full purchase cost, record every due date and test the plan against essential bills before choosing BNPL. Interest-free does not automatically mean fee-free or affordable.
Before selecting buy now, pay later at a Black Friday checkout, write down the entire repayment schedule. The important question is not whether today’s instalment fits your balance. It is whether every remaining payment fits alongside rent, food, transport, other debts and plans you already have.
The Consumer Financial Protection Bureau’s fee guidance explains that many BNPL loans do not charge interest but can charge late fees. Automatic repayment can also expose you to bank overdraft or non-sufficient-funds fees when the linked account lacks enough money. Check the individual agreement rather than relying on the checkout headline.
Start with the purchase, not the instalment
Record the cash price, delivery charge, taxes shown at checkout and any optional extras. Compare that complete total with the amount you will repay under the offered plan. Do not assume every BNPL product has the same number of payments, frequency or interest terms.
Use a discount calculator to check a stated reduction if that helps evaluate the purchase itself. Then put the discount aside and decide whether you need the item at the final price. A sale does not make borrowing affordable, and a claimed saving does not offset a payment you cannot make.
Save the actual agreement before accepting. It should let you identify the lender, amount borrowed, payment schedule, interest if any, fees and contact route. If you cannot find or understand the terms, pause rather than guessing what the attractive first-payment display means.
Build one calendar for all your plans
Create a simple list or spreadsheet with these columns:
- Retailer, order reference and BNPL provider.
- Full purchase total and unpaid balance.
- Every due date and the exact amount due.
- Payment account or card and whether autopay is enabled.
- Return, dispute or support status, with any confirmed schedule change.
Use one row for each payment, not merely one row for each purchase. Combine existing plans with the proposed new one and sort the rows by date. Several manageable-looking plans can become a difficult cluster of withdrawals.
A date difference calculator can help check how far a due date is from payday. It does not know the lender’s processing cutoff, your bank’s settlement timing or whether a payment date moves around holidays. Copy contractual dates exactly and confirm any uncertainty with the provider.
Test cash flow before accepting
Mark reliable income dates and essential bill dates on the same calendar. Work through the expected balance after each item rather than comparing monthly income with monthly instalment totals. Money arriving later in the month cannot necessarily cover a withdrawal earlier in it.
Include existing card repayments and other loan commitments. Avoid counting an expected refund, resale proceeds or uncertain overtime as money already available. If the schedule leaves no workable margin for ordinary changes, reducing the purchase or postponing it may be safer than adding another plan.
A percentage calculator can show what share of your own budget the repayments represent. There is no universal percentage in this guide that makes BNPL safe. The useful result is a realistic dated plan, not a score that approves more borrowing.
Check autopay and fee terms separately
Read which account will be charged, when the first payment is collected and whether the provider may retry a failed debit. Ask how to update a payment method and how long a change takes. Keep reminders even if autopay is on; automation does not ensure sufficient funds.
Review the lender’s late fee policy and your bank’s relevant overdraft or insufficient-funds terms. Do not assume declining an overdraft option eliminates every possible bank fee. The CFPB warns that costs and policies vary by lender, and bank charges can be separate from the BNPL agreement.
Cancelling an automatic payment does not by itself cancel a debt. If a withdrawal date will not work, contact the provider before it arrives and ask what options exist. Obtain any agreed change in writing and update the calendar only when confirmed.
Treat returns as a separate process
A returned parcel and an adjusted lending balance are different events. Follow the merchant’s return procedure and the provider’s instructions for reporting a return or dispute. Save tracking, receipts and correspondence, then check that any accepted refund appears in the loan account.
Do not assume sending an item back automatically pauses payments. Ask the provider whether a pause applies to your specific case and what you should pay while it is reviewed. Keep checking the schedule until the account reflects the confirmed outcome. This guide does not promise credit-card-equivalent protections or a universal refund right.
Act early if a payment becomes unaffordable
Contact the lender through its official channel before a missed payment where possible. Explain the problem, ask about available assistance and retain the response. The CFPB notes that unpaid debt may be sent to collection and that missed payments might affect credit if payment information is reported.
The CFPB’s archived 2022 industry study provides historical context about overlapping borrowing and uneven protections. It is not a statement of current 2026 law or current market growth. This article uses no forecast of Black Friday borrowing and no assumed lender-wide policy.
Research reviewed November 17, 2026. This US-focused guide is general budgeting information, not personal financial or legal advice.
Frequently asked questions
Does interest-free mean fee-free?
No. Late fees and separate bank charges may still apply. Read both the loan and payment-account terms.
Can autopay cause an overdraft?
It can expose you to overdraft or non-sufficient-funds charges if the linked account lacks enough money, depending on the account terms.
How do I track several plans?
Put each individual payment into one dated calendar and compare it with income and essential bills.
Does a return stop payments automatically?
Do not assume so. Follow the provider’s return process and obtain confirmation of any pause or revised schedule.
Can a missed payment affect my credit?
It might if the lender or a debt collector reports payment information. Collection is also a possible consequence of nonpayment.
Should I use a standard loan repayment calculator?
Not as a substitute for the agreement. Copy the provider’s exact amounts and dates; BNPL schedules can differ from amortizing loans.
Useful on MayreDukaan
Sources
Facts last checked against these sources on Nov 16, 2026, 8:44 PM ET.
Images: Original AI-generated illustration by MayreDukaan; conceptual, not a product screenshot.
More trending articles
 Black Friday and Cyber MondayFake Delivery Texts: Verify a Parcel Without Clicking17 Nov 2026 · 4 min read
 Black Friday and Cyber MondayAmazon Black Friday 2026: Dates, Access and Returns16 Nov 2026 · 5 min read
 Shopping and DealsGift-Card Tampering: Check the Card and Save Proof17 Nov 2026 · 4 min read
 Business and RetailRequest Customer Reviews Without Buying Praise17 Nov 2026 · 4 min read